Record 0DTE options volume is one-day leverage, not market depth.期权成交量创纪录是一天内的杠杆,不是市场深度。
Cboe said Thursday that zero-days-to-expiry (0DTE) options hit a record 24.2 million contracts a day last quarter, about 36% of all US options volume, as record 0DTE activity drove its options revenue higher. The common read treats that as depth. It is closer to the opposite.
A 0DTE contract rents large notional exposure for a few hours against a small premium. Most buyers hand that premium back as decay by the close; the dealers who sold it hedge by trading the underlying. So as same-day options climb toward a third of the tape, more of each day's price path is hedging flow, not information, and intraday swings get amplified for people who never touched an option.
Leverage amplifies both ways, but unevenly: the buyer carries the decay, the market carries the noise. The useful read is about sizing rather than direction. A same-day option is time-boxed leverage. Size it by what you can lose in hours, not by how cheap the premium looks. This breaks if 0DTE's share keeps climbing while realized intraday volatility falls. Research, not investment advice.
Cboe 周四(10 月 30 日)表示,上个季度零日到期(0DTE)期权成交量创下日均约 2420 万张的纪录,约占全美期权成交量的 36%;正是创纪录的 0DTE 活动推高了它的期权业务收入。普遍的读法把这当成深度,其实几乎相反。
一张 0DTE 合约,用很小的权利金,就能租到几个小时的大额名义敞口。多数买方到收盘时,会把这笔权利金以时间价值衰减的形式还回去;卖出这些合约的做市商则通过买卖标的资产来对冲。于是当『当天到期』的期权占到成交量的近三分之一,每天的价格路径里就有更多部分来自对冲盘的流动,而不是新信息,日内波动因此被放大,连从没碰过期权的人也一起承受。
杠杆向两个方向放大,但并不均匀:买方承担衰减,市场承担噪声。真正有用的判断是关于仓位大小,而不是方向。当天到期的期权是一笔上了时钟的杠杆——按你能在几个小时内亏掉多少来定仓位,而不是按权利金看起来多便宜。这会被推翻,如果 0DTE 的占比继续上升、而实际的日内波动率反而下降。研究,不构成投资建议。

Add WAKENEX as a preferred source on Google在 Google 把 WAKENEX 设为首选来源
READ NEXT接着读
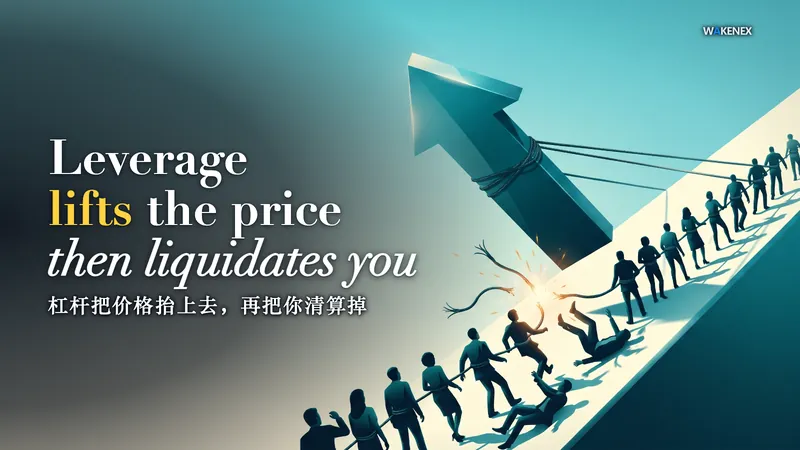
Shiba Inu's drop today was self-inflicted: the leveraged bulls liquidated themselves.柴犬币(SHIB)今天这波下跌,砸盘的不是看空的人,是加了杠杆的看多的人自己。
On Oct 30, about $20 million of SHIB positions were liquidated within 24 hours — longs absorbed roughly $12.9 million, shorts about $7 million — and even now long positions still outnumber shorts by about 2.71 to 1. The price didn't fall on "bad news." A crowd that borrowed money to go long hit maintenance margin on one small dip, got force-closed at market, and was made to sell; those sells pushed the price lower, triggered the next wave of liquidations, and it cascaded.
10 月 30 日,SHIB 在 24 小时内被强平约 2000 万美元,其中多头吃掉约 1290 万、空头约 700 万——而此刻看多仓位仍是看空的约 2.71 倍。价格不是被『利空』砸下来的,是一批借钱做多的人在一次小幅回调里触及维持保证金、被系统按市价强制平仓、被迫卖出,这些卖单又压低价格、触发下一批强平,连环滚下去。
Open note阅读短评
A search API below cost isn't a discount; it buys the doorway.低于成本定价的搜索API并非折扣,而是在购买入口。
Baidu just cut the promotional price of its Search AI API to 4.9 yuan per 1,000 calls at a 2026-10-30 Beijing briefing, set deliberately just under DeepSeek's standard 5 yuan. A search API is an agent's eyes: it crawls, indexes and returns live web results for the model, and that carries real compute and bandwidth cost that cannot be near zero.
百度把搜索 AI API 的活动价压到千次 4.9 元,专门卡在 DeepSeek 标准价 5 元之下(10 月 30 日北京发布会)——这不是让利,是用低于成本的价格去抢每个 AI 智能体调用网络的那道『入口』。
Open note阅读短评
Binance is the biggest exchange, and scale is why this hurt.Binance 是规模最大的交易所,而正是这种规模放大了此次冲击的影响。
Being the biggest didn't make customer coins safer; it widened the blast radius. On Oct 29 a stolen signing key took over one of its hot wallets and roughly 195,470 ETH was swept out. Per Binance's own Oct 1 reserve data, the drained wallets were the ones backing customer ETH balances; after the hack its ETH is backed at only about 94%.
币安是全球最大的加密货币交易所,但正是『最大』把这次事故放大到了极致:10 月 29 日,一把被盗的签名密钥接管了它的一个热钱包,约 19.5 万枚 ETH 被扫走——而据币安自己 10 月 1 日的储备数据,被掏空的恰恰是用来兑付用户 ETH 余额的那些钱包,事发后它的 ETH 兑付率只剩约 94%。
Open note阅读短评